Showing posts with label reserve currency. Show all posts

Wednesday, August 3, 2016

5 Things To Focus On

Via Fasanara Capital's Francesco Filia,
Oil failed to conquer and retain 50$ and is now falling off visibly again: both Brent and WTI lost ~20% since mid-June highs. This is in stark contrast to the price action in Base Metals, as they push through new ytd highs despite weakness in the global economy. We also keep a close look to the USD, which has historically been well correlated to Oil prices. We continue to expect Oil to move erratically, alongside a downward trend, which will eventually take it into new lows. We also expect Base Metals to eventually give in too and remain at levels in line with a depressed economy entangled in structural deflationary trends.
BRENT is currently playing with 200days moving average
During the last 5 years, at times Brent prices cut through 50d, 100d and 200d MAs, a sudden drop followed.


OIL and BASE METALS decoupling, again, while moving in opposite directions
Base metals have closed their underperformance gap vs Oil, which opened up in May, as they moved higher in absolute terms while Oil fell. All this happened despite red-flashing signs of slowdown in the global economy.


Brent (inverted) vs USD Index
Historically, the USD has been nicely correlated to Oil prices. Lower levels for Oil normally coincided with higher level of USD (alongside various fundamental drivers). This is not the case at present, as markets assess the case for Oil to drop more violently from here. The dollar may experience a leg up if Brent prices keep falling.


US Earnings and US Sales confirm their downward trend: behind the smoke and mirrors of headlines beats on skilfully lowered guidance - a trend we got accustomed to in recent past, US earnings’ and Sales keep deteriorating, having been in a downward trend for the last 5 quarters. Valuations are over-stretched as a consequence of (i) lower bond yields distorting equity vs bonds valuations, and (ii) generous 2017 earnings’ upgrade expectations. Equity markets' consensus for 2017 seems then to entail that (i) bonds are wrong in factoring in a depressed economy (although that is the reason for the permanent Central Bank monetary expansion itself), and(ii) escape velocity of GDP is just around the corner. We expect such expectations to be misplaced (see May 2016 Investment Outlook), complacency to gradually fade (see Article: S&P the last castle to fall). We expect extreme valuations to give in, and cheaper US equities. To us, it is more a question of 'when', rather than 'if'.
US Earnings and avg. Sales are trending lower
Earnings/Sales moving lower but the market simply postpones the robust recovery to come, by expanding multiples to historically-silly levels. Just minor delays on the loose schedule of a strong US economy, or markets in denial?


S&P implied volatility moved to new historical lows in recent past: lower implied volatility can only exacerbate the virulence of any downside movements, as and when they occur, for it seduces weak-hands bond-type investors into equity markets, whose mandate is not drafted for stomaching equity-type volatility bouts, resulting in hot money flows at such inflection points when the market heads lower. Low historical volatility also entices Risk Parity strategies, algorithms / CTAs, and more leverage, ready to evaporate quickly once that low volatility gives in. Low volatility is a value trap: it is not so much a reason for an equity sell-off, but rather it may affect its shape and tempo, should a sell-off occur, as we expect.
US Banks have decoupled from US rates: while EU and Japanese banks have closely followed the path of interest rates / the slope of the yield curve, US Banks have decoupled markedly from them. We expect this divergence to correct in the following weeks, as US Banks move lower more than rates, or move higher less than rates. Our case for the EU Banking sector to hit new lows in the near future (see Article) - on grounds of profitability more than solvency - can be extended to US banks too. We look at this as a top value opportunity for the months to come.
US Banks have decoupled from US yields
The three following charts shows US, EU and Japanese Banks against their respective government bond yields. Comparing bank equities to the slope of the yield curve leads into similar conclusions.
While EU and JPN banks have closely followed the rates, US banks diverged from the level of interest rates. We may expect this to correct in the following weeks


Japanese yields experienced their largest 4-days sell-off since 2003: the 10yr JBG yield rose ~23 bps since the BoJ meeting’s disappointment of last Thursday, where Kuroda ruled out the possibility of additional rate cuts. We follow closely the moves on JGBs, to see if they may lead to a 2015-type Bunds riot or 2013 l-type Taper Tantrum moment, while only temporarily so.
10yr JGB’s yield experience its largest 4 days rise since 2003
This is a trend to be closely followed, since it may lead to a larger sell-offs in US Treasuries and EU Bonds, although temporarily, as it was the case in April/May 2015.


*  *  *

Tuesday, May 31, 2016

The Fascinating Story Of How The Petrodollar Was Born And Lived In Secrecy For Over 40 Years

Tyler Durden's picture

http://www.zerohedge.com/news/2016-05-31/secret-story-how-saudi-petrodollar-deal-was-born
For decades, the story of Saudi Arabia recycling petrodollars, i.e., funding the US deficit by buying US Treasuries with proceeds of its crude oil sales (mostly to the US), while the US sweetened the deal by providing the Saudis with military equipment and supplies, remained entirely in the conspiracy realm, with no confirmation or official statement from the US Treasury department.
Now, that particular "theory" becomes the latest fact, thanks to a fascinating story by Bloomberg which gives the background and details of secret meeting between then-US Treasury secretary William Simon and his deputy, Gerry Parsky, and members of the Saudi ruling elite, and lays out the history of how the petrodollar was born.
Here is the background:
It was July 1974. A steady predawn drizzle had given way to overcast skies when William Simon, newly appointed U.S. Treasury secretary, and his deputy, Gerry Parsky, stepped onto an 8 a.m. flight from Andrews Air Force Base. On board, the mood was tense. That year, the oil crisis had hit home. An embargo by OPEC’s Arab nations—payback for U.S. military aid to the Israelis during the Yom Kippur War—quadrupled oil prices. Inflation soared, the stock market crashed, and the U.S. economy was in a tailspin.

Officially, Simon’s two-week trip was billed as a tour of economic diplomacy across Europe and the Middle East, full of the customary meet-and-greets and evening banquets. But the real mission, kept in strict confidence within President Richard Nixon’s inner circle, would take place during a four-day layover in the coastal city of Jeddah, Saudi Arabia.

The goal: neutralize crude oil as an economic weapon and find a way to persuade a hostile kingdom to finance America’s widening deficit with its newfound petrodollar wealth. And according to Parsky, Nixon made clear there was simply no coming back empty-handed. Failure would not only jeopardize America’s financial health but could also give the Soviet Union an opening to make further inroads into the Arab world.

It “wasn’t a question of whether it could be done or it couldn’t be done,” said Parsky, 73, one of the few officials with Simon during the Saudi talks
As noted above, the framework of the required deal was simple: the U.S. would buy oil from Saudi Arabia and provide the kingdom military aid and equipment. In return, the Saudis would plow billions of their petrodollar revenue back into Treasuries and finance America’s spending.
The man leading the US negotiation, US Treasury Secretary William Simon, had just done a stint as Nixon’s energy czar, and "seemed ill-suited for such delicate diplomacy. Before being tapped by Nixon, the chain-smoking New Jersey native ran the vaunted Treasuries desk at Salomon Brothers. To career bureaucrats, the brash Wall Street bond trader—who once compared himself to Genghis Khan—had a temper and an outsize ego that was painfully out of step in Washington. Just a week before setting foot in Saudi Arabia, Simon publicly lambasted the Shah of Iran, a close regional ally at the time, calling him a “nut.”
But Simon, better than anyone else, understood the appeal of U.S. government debt and how to sell the Saudis on the idea that America was the safest place to park their petrodollars. With that knowledge, the administration hatched an unprecedented do-or-die plan that would come to influence just about every aspect of U.S.-Saudi relations over the next four decades (Simon died in 2000 at the age of 72).
In the beginning it wasn't easy: "it took several discreet follow-up meetings to iron out all the details, Parsky said."
But at the end of months of negotiations, Bloomberg writes, there remained one small, yet crucial, catch: King Faisal bin Abdulaziz Al Saud demanded the country’s Treasury purchases stay “strictly secret,” according to a diplomatic cable obtained by Bloomberg from the National Archives database."
The secret remains... until May 16 when the US Treasury for the first time ever revealed the full extent of Saudi TSY holdings.


Bloomberg adds that with a handful of Treasury and Federal Reserve officials, the secret was kept for more than four decades—until now. "In response to a Freedom-of-Information-Act request submitted by Bloomberg News, the Treasury broke out Saudi Arabia’s holdings for the first time this month after “concluding that it was consistent with transparency and the law to disclose the data,” according to spokeswoman Whitney Smith. The $117 billion trove makes the kingdom one of America’s largest foreign creditors."
The TIC data released later that day confirmed the FOIA response.
To be sure, as we commented in mid-May, it is very likely that the Treasury report is incomplete, and that the Saudis also own hundreds of billions in Treasurys held in custody with offshore trading centers such as Euroclear. After all, the current tally represents just 20 percent of its $587 billion of foreign reserves, well below the two-thirds that central banks typically keep in dollar assets
What’s more, the commitment to the decades-old policy of “interdependence” between the U.S. and Saudi Arabia, which arose from Simon’s debt deal and ultimately bound together two nations that share few common values, is showing signs of fraying. America has taken tentative steps toward a rapprochement with Iran, highlighted by President Barack Obama’s landmark nuclear deal last year. The U.S. shale boom has also made America far less reliant on Saudi oil.
Needless to say, the real total notional amount of Saudi holdings will eventually become known, especially if the middle-eastern nation follows through with its threat of liquidating some or all of them.  What is more notable, however, is that with the first disclosure of this data since the birth of the petrodollar, something appears to have changed:
What’s more, the commitment to the decades-old policy of “interdependence” between the U.S. and Saudi Arabia, which arose from Simon’s debt deal and ultimately bound together two nations that share few common values, is showing signs of fraying. America has taken tentative steps toward a rapprochement with Iran, highlighted by President Barack Obama’s landmark nuclear deal last year. The U.S. shale boom has also made America far less reliant on Saudi oil.

“Buying bonds and all that was a strategy to recycle petrodollars back into the U.S.,” said David Ottaway, a Middle East fellow at the Woodrow Wilson International Center in Washington. But politically, “it’s always been an ambiguous, constrained relationship.”
One thing that certainly changed is that in a world where central banks are ravenously buying up each others' (and their own) debt, the need for Petrodollar recyclers such as Saudi Arabia is no longer there. But that was not always the case:
[B]ack in 1974, forging that relationship (and the secrecy that it required) was a no-brainer, according to Parsky, who is now chairman of Aurora Capital Group, a private equity firm in Los Angeles. Many of America’s allies, including the U.K. and Japan, were also deeply dependent on Saudi oil and quietly vying to get the kingdom to reinvest money back into their own economies.

"Everyone—in the U.S., France, Britain, Japan—was trying to get their fingers in the Saudis’ pockets,” said Gordon S. Brown, an economic officer with the State Department at the U.S. embassy in Riyadh from 1976 to 1978. For the Saudis, politics played a big role in their insistence that all Treasury investments remain anonymous.
America's reliance on Saudi Arabia to fund its deficit - and obtain a cheap price for oil - meant that the kingdom would be granted Platinum status in every form of interaction with the US.
Tensions still flared 10 months after the Yom Kippur War, and throughout the Arab world, there was plenty of animosity toward the U.S. for its support of Israel. According to diplomatic cables, King Faisal’s biggest fear was the perception Saudi oil money would, “directly or indirectly,” end up in the hands of its biggest enemy in the form of additional U.S. assistance.

Treasury officials solved the dilemma by letting the Saudis in through the back door. In the first of many special arrangements, the U.S. allowed Saudi Arabia to bypass the normal competitive bidding process for buying Treasuries by creating “add-ons.” Those sales, which were excluded from the official auction totals, hid all traces of Saudi Arabia’s presence in the U.S. government debt market.

“When I arrived at the embassy, I was told by people there that this is Treasury’s business,” Brown said. “It was all handled very privately.”

* * *
Another exception was carved out for Saudi Arabia when the Treasury started releasing monthly country-by-country breakdowns of U.S. debt ownership. Instead of disclosing Saudi Arabia’s holdings, the Treasury grouped them with 14 other nations, such as Kuwait, the United Arab Emirates and Nigeria, under the generic heading “oil exporters”—a practice that continued for 41 years.
Meanwhile, Saudi Arabia continued buying: by 1977, Saudi Arabia had accumulated about 20 percent of all Treasuries held abroad, according to The Hidden Hand of American Hegemony: Petrodollar Recycling and International Markets by Columbia University’s David Spiro.

The deal led to assorted headaches: "an internal memo, dated October 1976, detailed how the U.S. inadvertently raised far more than the $800 million it intended to borrow at auction. At the time, two unidentified central banks used add-ons to buy an additional $400 million of Treasuries each. In the end, one bank was awarded its portion a day late to keep the U.S. from exceeding the limit.
Most of these maneuvers and hiccups were swept under the rug, and top Treasury officials went to great lengths to preserve the status quo and protect their Middle East allies as scrutiny of America’s biggest creditors increased.

Over the years, the Treasury repeatedly turned to the International Investment and Trade in Services Survey Act of 1976—which shields individuals in countries where Treasuries are narrowly held—as its first line of defense.

The strategy continued even after the Government Accountability Office, in a 1979 investigation, found “no statistical or legal basis” for the blackout. The GAO didn’t have power to force the Treasury to turn over the data, but it concluded the U.S. “made special commitments of financial confidentiality to Saudi Arabia” and possibly other OPEC nations.

Simon, who had by then returned to Wall Street, acknowledged in congressional testimony that “regional reporting was the only way in which Saudi Arabia would agree” to invest using the add-on system.
Ultimately, Saudi dominance in the US Treasury market meant they were untouchable. "It was clear the Treasury people weren’t going to cooperate at all,” said Stephen McSpadden, a former counsel to the congressional subcommittee that pressed for the GAO inquiries. “I’d been at the subcommittee for 17 years, and I’d never seen anything like that."
Today, Parsky says the secret arrangement with the Saudis should have been dismantled years ago and was surprised the Treasury kept it in place for so long. But even so, he has no regrets. Doing the deal “was a positive for America”, he says cited by Bloomberg.
And with that the story of how the Petrodollar was born is now public information, something which Saudi Arabia may not be too happy with. For the sake of the US, it better have its ducks in order because the release of this story simply means that the US Treasury is confident it will no longer have a strategic need for its long-time Saudi partner. The Fed, which has implicitly stepped into the Saudi role, better not disappoint.

In Its First Ever Bond Sale, A Cash-Starved Saudi Arabia Is Looking To Issue $15 Billion

Tyler Durden's picture


http://www.zerohedge.com/news/2016-05-31/its-first-ever-bond-sale-cash-starved-saudi-arabia-looking-issue-15-billion
Last week the bond market was stunned by the unprecedented demand for sovereign paper issued by the middle-eastern nation of Qatar, which announced it would issue $9 billion in Eurobonds (in three maturities), more than double what had been originally expected by the market, and well below the total demand for Qatar sovereign paper: according to Reuters, the issue was massively oversubscribed, with over $23 billion in soft orders.
Some were concerned that this massive bond issuance would "reprice" the local bond market and put on hold any new incremental issuance by Qatar's neighbors, most notably Saudi Arabia, which has been very vocal about its own intentions to sell debt in the coming weeks and which, in light of its surging budget deficit ballooning as a result of persistently low oil prices, desperately needs an outside cash infusion.
We said that these concerns were materially overblown as Qatar was merely the latest example of the scramble for yield in the current "risk on" environment, and if anything Qatar's sale demonstrated that any attempt by Saudi Arabia to fund its budget needs would be ridiculously easy.
Sure enough, this was confirmed just days later when earlier today Bloomberg reported that Saudi Arabia is considering the sale of as much as $15 billion of bonds this year, "encouraged by investor demand for Qatar’s recent issue" citing people with knowledge of the matter said.
The details: Saudi Arabia is weighing a sale of $10 billion to $15 billion after the end of Ramadan in July, adding no final decision has been made and the discussions are still at a preliminary stage. It would be Saudi Arabia’s first bond sale in international capital markets. We think that absent another global market swoon, the final notional amount issued will be well greater than "only" $15 billion.
While Saudi Arabia is still sitting on nearly $600 billion in foreign-exchange reserves, the country has burned through $140 billion in reserves since the end of 2014. And the IMF warned the Saudis could eventually run out of cash.
This is not Saudi Arabia's first recent approach to capital markets: in April the kingdom raised a $10 billion loan from a group of banks, its first loan in 25 years. Last year, the Saudis tapped the local bond market for the first time in eight years, raising at least $4 billion.
But this would be the first time Saudi Arabia has issued international bonds. And it will be a whopper.
CNN also quotes John Sfakianakis, a former official in Saudi Arabia's Ministry of Finance who said the sale would likely take place over the next several months. "There is a need to cover the fiscal gap," said Sfakianakis, who is currently director of economic research at the Gulf Research Center in Riyadh, Saudi Arabia. "It's better for this money to come from other sources than reserve assets because as they get depleted that places a bigger risk over the medium to long-term."
Bloomberg adds that Saudi Arabia has invited banks to arrange the bond sale. The country expects to issue a “significant” amount, the people said at the time, without giving more details.
Saudi Arabia's move is hardly a surprise: the country is merely taking advantage of an unprecedented bond bubble inflated by global central banks, where $9.9 trillion in sovereign paper is now trading with negative yields.
As a result, governments in the six-nation Gulf Cooperation Council, which includes the two-biggest Arab economies of Saudi Arabia and the United Arab Emirates, are turning to public markets to raise funds after a plunge in oil prices led to higher budget deficits. Qatar last week attracted $23 billion in orders for its $9 billion sale, the biggest-ever bond issue from the Middle East. Abu Dhabi raised $5 billion from the sale of five and 10 year securities in April.
Some more:
The debut bond will follow the country’s first loan in at least 15 years as it seeks to fill a budget hole estimated at about $100 billion this year. Saudi Arabia sealed a $10 billion facility in April, three people with knowledge of the matter said at the time.

The country also hired HSBC Holdings Plc banker Fahad Al Saif to start a debt management office that will be responsible for the international bond sale, two separate people with knowledge of the matter said this week. Al Saif joined the Ministry of Finance on an open-ended secondment from HSBC’s Saudi British Bank, the people said.

The country is undergoing its biggest-ever economic shakeup, led by Deputy Crown Prince Mohammed bin Salman, as it prepares for the post-oil era following the plunge in crude prices that started in 2014. One of the government’s biggest challenges will be navigating the worst economic slowdown since the global financial crisis as authorities cut spending to plug a budget deficit that reached about 15 percent of gross domestic product in 2015.
The biggest irony here is that while Saudi Arabia has been implicitly fighting the Fed (and other central banks), who have generously funded the US shale industry with hundreds of billions in junk bonds over the past decade, the same industry of "high cost producers" that Saudi Arabia is eager to put out of business indefinitely, it is the same Fed that is coming to Saudi's rescue now by stoking demand for any deficit-funding paper Saudi Arabia may and will issue.
The good news for Saudi Arabia is that the new debt funds will be promptly used to address gaping fiscal holes in the Saudi economy: Moody's recently warned of the social impact of policy reforms in Saudi Arabia and other Gulf countries where "governments are under pressure to continue redistributing oil revenues to their populations to avoid economic-related civil unrest."
But what the inevitable record bond issuance out of Saudi Arabia means, is that the deflationary pressure on oil will persist, as the largest crude oil exporter will not need to rationalize oil supply for the foreseeable future by cutting supply to boost prices. Instead, Saudi can simply fund its budget shortfall by appealing to the same bond investors who are keeping shale afloat, while maintaining its strategy of keeping the oil market continuously oversupplied.

Monday, May 23, 2016

De-Petrodollar-ization Esclates - China Imports Record Amount Of Russian Oil In April

Tyler Durden's picture

http://www.zerohedge.com/news/2016-05-23/de-petrodollar-ization-esclates-china-imports-record-amount-russian-oil-april
We have reported for years that Russia and China have been doing everything they can to displace the use (and influence) of the US dollar.
The US of course, either oblivious or too arrogant to care, has continued to bring Russia and China together by annoying both equally with its incessant meddling. Recall that recently both China and Russia have had to warn the US about its insistence on flying reconnaissance planes too close to their borders.
Of course, as the US has been playing geopolitical games, China and Russia have been working on strengthening their relationship with one another. At the end of 2015, China had become Russia's biggest oil customer, and as of April, Russian oil shipments to China hit a record high. Russia has also surpassed Saudi Arabia as the biggest crude exporter to China.

Russia Today has more
Beijing has ramped up imports of Russian oil by 52.4 percent last month compared to a year earlier. China's General Administration of Customs calculated a record 4.81 million tons.

In March, China bought 4.65 million tons of oil from Russia.

Russia, Saudi Arabia and Angola were China’s three major oil suppliers last month.

April imports from Saudi Arabia fell by 22 percent year-on-year to 4.12 million tons. In March, China imported 3.98 million tons of oil from the country.

China increased year-on-year oil imports from Angola last month by 39 percent to 3.98 million tons. Imports from Iran in April fell by 5.1 percent yoy to 2.76 million tons.

An International Energy Agency report showed that at the end of 2015 Russia overtook Saudi Arabia as the biggest crude exporter to China.
Russian exports to China have doubled over the past five years, and supply is expected to continue to be strong. Transneft's Vice-President Sergey Andropov said that China is expected to import 27 million tons of Russian crude this year via the Eastern Siberia-Pacific Ocean (ESPO) pipeline. The volume underscores the significance of contracts signed  in 2009 by Rosneft, Transneft, and China National Petroleum Corporation to have Russia supply oil to China through the ESPO.
Russian exports to China have more than doubled over the past five years, up by 550,000 barrels a day. Moscow and Beijing have significantly increased energy cooperation, with a wide range of multibillion dollar projects.

Russian oil transport monopoly Transneft’s Vice-President Sergey Andropov said in March that China is ready to import 27 million tons of Russian crude this year via the Eastern Siberia-Pacific Ocean (ESPO) pipeline. Supplies to China through the ESPO pipeline started in 2011 after Rosneft, Transneft and China National Petroleum Corporation (CNPC) signed contracts two years earlier. Currently five million tons of crude are supplied through the pipeline annually, and this is expected to rise to 15 million tons a year.

Experts say Chinese imports of Russian oil are likely to stay high over the coming years due to long-term crude supply contracts and rising demand from the world's second biggest oil consumer.
* * *
There is an underlying theme here that cannot be ignored.
Whatever the US has been focusing on, whether it's commissioning $4.4 billion warships, wargaming in the name of "regional stability", or arguing over LGBT rights and confederate flags, it is neither productive, nor helping its global economic standing. One day when the USD is no longer the reserve currency, and all of the games the Federal Reserve plays to allow fiscal policy to go unchecked are no longer an option, we suspect that it will wish it had done things quite differently.

Friday, May 20, 2016

Something Stunning Is Taking Place Off The Coast Of Singapore

http://www.zerohedge.com/news/2016-05-20/something-stunning-taking-place-coast-singapore

Tyler Durden's picture


   "I've been coming to Singapore once a year for the last 15 years, and flying in I have never seen the waters so full of idle tankers,"
   - Senior European oil trader a day after arriving in the city-state.

Back in November, when the world-record crude inventory glut was still in its early innings, we showed what we then thought was a disturbing image of dozens of oil tankers on anchor near the US oil hub of Galveston, TX, unwilling to unload their cargo at what the owners of the oil thought was too low prices.

* * *
Little did we know that just a few months later this seemingly unprecedented sight of clustered VLCCs would be a daily occurrence as oil producers, concerned by Cushing hitting its operating capacity, would take advantage of oil curve contango to store their oil offshore indefinitely.
However, while the "parking lot" off Galveston has since normalized, something shocking has emerged and continued to grow half way around the world, just off the coat of Singapore. This.


The red dots show ships either at anchor or barely moving, either oil tankers or cargo, which have made the Straits of Malacca, one of the world's most important shipping lanes which carries about a quarter of all seaborne oil primarily from the Persian Gulf headed to China, into a "bumper to bumper" parking lots of ships with tens of millions of barrels in combustible cargo.
it is also the topic of the latest Reuters expose on the historic physical crude oil glut which continues to build behind the scenes, and which so far has proven totally immune to dissipation as a result of the sharp increase in oil prices over the past three months.
Indeed, as Reuters notes, prices for oil futures have jumped by almost a quarter since April, lifted by severe supply disruptions caused by triggers such as Canadian wildfires, acts of sabotage in Nigeria, and civil war in Libya. And yet flying into Singapore, the oil trading hub for the world's biggest consumer region, Asia, reveals another picture: that a global glut that pulled down prices by over 70 percent between 2014 and early 2016 is nowhere near over, and that financial traders betting on higher crude oil futures may be in for a surprise from the physical market.
"I've been coming to Singapore once a year for the last 15 years, and flying in I have never seen the waters so full of idle tankers," said a senior European oil trader a day after arriving in the city-state.
As Asia's main physical oil trading hub, the number of parked tankers sitting off Singapore's coast or in nearby Malaysian waters is seen by many as a gauge of the industry's health.  Judging by this, oil markets are still sickly: a fleet of 40 supertankers is currently anchored in the region's coastal waters for use as floating storage facilities.
The glut is not only constant but is rising with every passing week: the tankers are filled with 47.7 million barrels of oil, mostly crude, up 10 percent from the previous week, according to newly collected freight data in Thomson Reuters Eikon.
What is curious is that the glut is persisting despite seemingly relentless demand by China. Earlier today Bloomberg calculated that 74 VLCCs are bound for China, the highest in 3 weeks, and up from 69 a week earlier. Still the inert glut off Singapore is enough oil to satisfy five working days of Chinese demand, suggesting recent supply disruptions - which have mostly occurred in the Americas, Africa and Europe - have done little to tighten supply in Asia as Middle East producers keep output near record volumes in a bid to win market share.
"The volumes of oil stored at sea in South East Asia - predominantly Singapore and Malaysia - appear to have increased significantly," said Erik Broekhuizen, Global Manager of tanker research and consultancy at New York-based shipping brokerage Poten & Partners. "The current volumes are the highest for at least the last five years."
What is taking place in the oil market appears to be merely the latest disconnect between the paper and physical markets, something quite familiar to precious metals traders in recent years. As Reuters notes, many participants in the physical market dispute recent notes from financial players like Goldman Sachs that forecast a further rise in crude futures. "There has been quite a bit of bullishness from hedge funds in recent months, betting on higher oil prices, and even the analysts at Goldman Sachs have recently turned more bullish on oil prices," said Ralph Leszczynski, head of research at ship broker Banchero Costa.
"Prices are unlikely to rise too much as the specter of glut is still there," he said. However, Leszczynski may be discounting just how powerful algo-driven momentum can be if, or especially when, it is completely disconnected from fundamentals.
* * *
While the sight of tankers at anchor is nothing new, this time something has changed.
Unlike before, when the contango of the oil curve made storing oil offshore profitable, this is no longer the case as contago-funded offshore profits have all but disappeared.
As a reminder, storing oil on ships can be profitable when prices for future delivery of crude are higher than in spot market, a term structure known as contango, as long as future prices are high enough to offset tanker charter costs. However, with the one-year contango for Brent futures collapsing from $7.60 per barrel in January to just $4, far below the $10 that traders say is currently required to make floating storage financially attractive, suddenly parking oil offshore leads to storage losses. The same goes for WTI. 
At a charter cost of more than $40,000 a day for a Very Large Crude Carrier (VLCC) that can store 2 million barrels, the contango is nowhere near steep enough to make it profitable to store oil on tankers for sale at a later date.


This has led to a dramatic development in the oil market: debt-funded storage. Reuters writes that the need to store oil is so strong that traders are calling up banks to finance storage charters despite there being no profit in keeping fuel in tankers at current rates.
"We are receiving unusually high amounts of queries to finance storage charters," said a senior oil trade financier with a major bank in Asia. "These queries come from traders fully aware that they will not make a profit from storing the oil. This isn't a trade play, it's the oil market looking for places to store unsold fuel," he added.
So why are the traders doing this?
Simple: they hope that oil prices will rise fast and soon enough where the capital appreciation in crude will more than make up for the incurrence of new debt which will be repaid with proceeds from "selling higher." The risk, of course, is that oil does not rise and should prices tumble, traders will not only have a capital loss on their hands, but be forced to deal with the excess leverage they had hoped would promptly disappear.
To be sure, while we have warned in the past about the danger of offshore storage becoming unprofitable and being brought back onto the land market, in the process launching a liquidation dumping scramble, it has never been this bad. A trade financier at a European bank said there had been a "spike in interest from oil traders to finance their storage needs" since the start of the year as onshore facilities were almost full.
Still, with record amounts of oil stored offshore and with the profit on such storage now shifting into a loss, many are scratching their heads how much longer this imbalanced, and bank funded, situation can persist.
"Floating storage is unattractive economically, given the current term structure in crude futures," BMI Research said this week. Despite this, BMI said that "the volume of crude in floating storage has risen sharply in recent months," adding that the phenomenon was global, with floating storage up 19.5 percent between the first quarters of 2015 and 2016.
"There is clearly still far too much physical crude going around for the glut to be over," said the European oil trader after flying in to Singapore.
The trader's conclusion: "And the paper market seems blissfully unaware of it."
He is right... for now. Because all that will take for even the algos to give up their relentless upward momentum, is for some of these tens of millions of barrels to finally come onshore, which now that contango is no longer profitable, is just a matter of time.
In the meantime, just keep track of the unprecedented parking lot of ships off the coast of Singapore: the larger it gets, the more violent the price drop will be once banks say "no more" to funding money losing charters.

Monday, May 9, 2016

Trump On Debt Renegotiation: "You Never Have To Default Because You Print The Money"

Tyler Durden's picture

http://www.zerohedge.com/news/2016-05-09/trump-debt-renegotiation-you-never-have-default-because-you-print-money

Following Donald Trump's Thursday comments that rising interest rates would be disastrous for the economy, saying that "we're paying a very low interest rate. What happens if that interest rate goes up 2, 3, 4 points?" hinting that the U.S. should "renegotiate longer-term debt" with creditors and that if the economy crashes he "can make a deal", various media outlets went to town on Trump, most notably the NYT, which took Trump to task:
Asked on Thursday whether the United States needed to pay its debts in full, or whether he could negotiate a partial repayment, Mr. Trump told the cable network CNBC, “I would borrow, knowing that if the economy crashed, you could make a deal.”

Such remarks by a major presidential candidate have no modern precedent. The United States government is able to borrow money at very low interest rates because Treasury securities are regarded as a safe investment, and any cracks in investor confidence have a long history of costing American taxpayers a lot of money.

Experts also described Mr. Trump’s proposal as fanciful, saying there was no reason to think America’s creditors would accept anything less than 100 cents on the dollar, regardless of Mr. Trump’s deal-making prowess.

“No one on the other side would pick up the phone if the secretary of the U.S. Treasury tried to make that call,” said Lou Crandall, chief economist at Wrightson ICAP. “Why should they? They have a contract” requiring payment in full.
As the NYT admits, when "pressed to elaborate on his remarks, Mr. Trump did appear to step back. He said that he was not suggesting a default, but instead that the government could seek to repurchase debt for less than the face value of the securities. The government, in other words, would seek to repay less money than it borrowed."
In any case, the confusion about Trump's intentions continued and ultimately led to his latest CNN appearance in which he explained what he meant earlier this morning.
"If interest rates go up, we can buyback debt at a discount if we are liquid enough as a country. People say I want to default on debt - these people are crazy. First of all you never have to default because you print the money I hate to tell you, so there is never a default. It was reported in the NYT that I want to default on debt - you know I am the king of debt, I love debt, but debt is tricky and its dangerous. But let me just tell you: if interest rates go up and bonds go down, you can buy debt - that's what I'm talking about. So here is the story, if we have an opportunity where interest rates go up and you can buy back debt at a discount. I always like to be able to do that if you can do that. That's all I was talking about, they have it like I'm going to go back to creditors and I am going to renegotiate or restructure debt. It's ridiculous."
Here is the clip:
http://www.cnn.com/video/api/embed.html#
Aside from the comment that "one never has to default if one is printing the money", which has not exactly led to favorable outcomes for countries which have done just that and the only difference in the case of the US is possession of the reserve currency for now, what Trump is really talking about is inflating away the debt, something the Fed and all other central banks have been desperately trying to do for the past 7 years, so far without much success. 
In effect, Trump's point is really just a continuation of Fed policies: boosting inflation, and leading to a spike in long end yields; all Trump does is explain mechanistically how the US can take advantage of this "debt inflation", which as he correctly points out, can simply be repurchased at a price well below par if rates are surging in effect reducing the nominal debt burden.
Which incidentally brings us back to Trump's point about wanting lower interest rates: if the "king of debt" is so eager to buyback debt at a discount, what he should be urging is not lower but far higher interest rates. Now that is a proposal the Fed, Goldman and all global banks would love to get behind, even if it means leaving the economy in a state of even bigger collapse...

Wednesday, April 20, 2016

What Everyone Is Missing In The Oil Supply/Demand Conundrum

Tyler Durden's picture

http://www.zerohedge.com/news/2016-04-19/what-everyone-missing-oil-supplydemand-conundrum
Submitted by Gail Tverberg via Our Finite World blog,
Oil production can be confusing because there are various “pieces” that may or may not be included. In this analysis, I look at oil production of the United States broadly (including crude oil, natural gas plant liquids, and biofuels), because this is the way oil consumption is defined. I also provide some thoughts regarding the direction of future world oil prices.
Figure 1. US Liquid Fuels production by month based on EIA March 2016 Monthly Energy Review Reports.
US oil production clearly flattened out in 2015. If we look at changes relative to the same month, one-year prior, we see that as of December 2014, growth was very high, increasing by 18.0% relative to the prior year.
Figure 2. US Liquids Growth Over 12 Months Prior based on EIA's March 2016 Monthly Energy Review.
Figure 2. US Liquids Growth Over 12 Months Prior based on EIA’s March 2016 Monthly Energy Review.
By December 2015, growth over the prior year finally turned slightly negative, with production for the month down 0.2% relative to one year prior. It should be noted that in the above charts, amounts are on an “energy produced” or “British Thermal Units” (Btu) basis. Using this approach, ethanol and natural gas liquids get less credit than they would using a barrels-per-day approach. This reflects the fact that these products are less energy-dense.
Figure 3 shows the trend in month-by-month production.
Figure 3. US total liquids production since January 2013, based on EIA's March 2016 Monthly Energy Review.
Figure 3. US total liquids production since January 2013, based on EIA’s March 2016 Monthly Energy Review.
The high month for production was April 2015, and production has been down since then. The production of natural gas liquids and biofuels has tended to continue to rise, partially offsetting the fall in crude oil production. Production amounts for recent months include estimates, and actual amounts may differ from these estimates. As a result, updated EIA data may eventually show a somewhat different pattern.
Taking a longer view of US liquids production, this is what we see for the three categories separately:
Figure 4. US Liquid Fuel Production since 1949, based on EIA's March 2016 Monthly Energy Review.
Figure 4. US Liquid Fuel Production since 1949, based on EIA’s March 2016 Monthly Energy Review.
Growth in US liquid fuel production slowed in 2015. The increase in liquid fuels production in 2015 amounted to 1.96 quadrillion Btus (“quads”), or about 59% as much as the increase in production in 2014 of 3.34 quads. On a barrels-per-day (bpd) basis, this would equate to roughly a 1.0 million bpd increase in 2015, compared to a 1.68 million bpd increase in 2014.
The data in Figure 4 indicates that with all categories included, 2015 liquids exceeded the 1970 peak by 16%. Considering crude oil alone, 2015 production amounted to 98% of the 1970 peak.
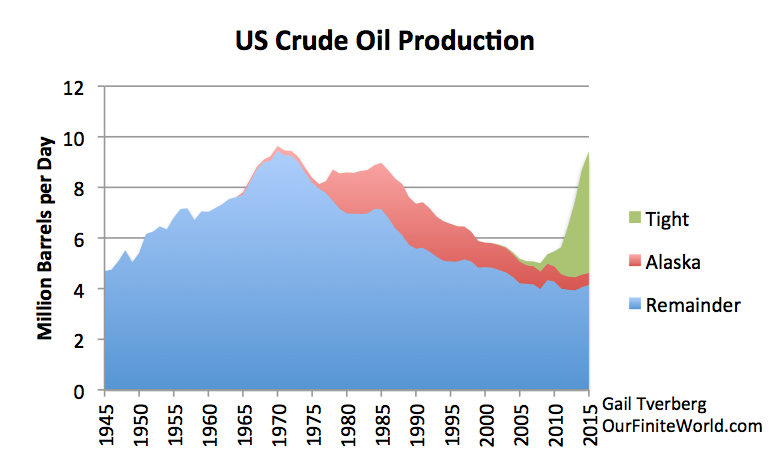
Figure 5 shows an approximate breakdown of crude oil production since 1945 on a bpd basis. The big spike in production is from tight oil, which is another name for oil from shale.
Figure 5. Oil crude oil production separated into tight oil (from shale), oil from Alaska, and all other, based on EIA oil production data by state.
Here again, US crude oil production in 2015 appears to amount to 98% of the 1970 crude oil peak. Thus, on a crude oil basis alone, we have not yet hit the 1970 peak.

Prospects for an Oil Price Rise

Most recent analyses of oil prices have focused on the amount of mismatch between supply and demand, and the need to craft a temporary agreement to reduce oil production. The thing that is missing in this discussion is an analysis of buying power of consumers. Is the problem a temporary problem, or a permanent one?
In order for oil product demand to keep rising, the buying power of consumers needs to keep rising. In other words, some combination of consumer wages and debt levels of consumers needs to keep rising. (Rising debt is helpful because, with more debt, it is often possible to buy goods that would not otherwise be affordable.)
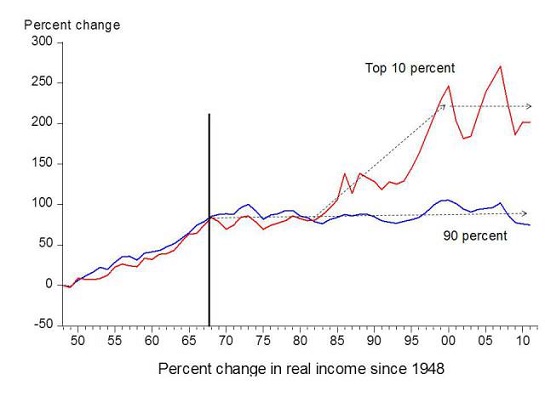
We know that in many countries, wages for lower-level workers have stagnated for a number of reasons, including competition with wages in lower-wage countries, computerization, and the use of automation (Figure 6). Thus, we know that low wages for a large share of consumers may be a problem.
Figure 6. Chart comparing income gains by the top 10% to income gains by the bottom 90% by economist Emmanuel Saez. Based on an analysis IRS data, published in Forbes.
Figure 6. Chart comparing US income gains by the top 10% to income gains by the bottom 90% by economist Emmanuel Saez. Based on an analysis IRS data, published in Forbes.
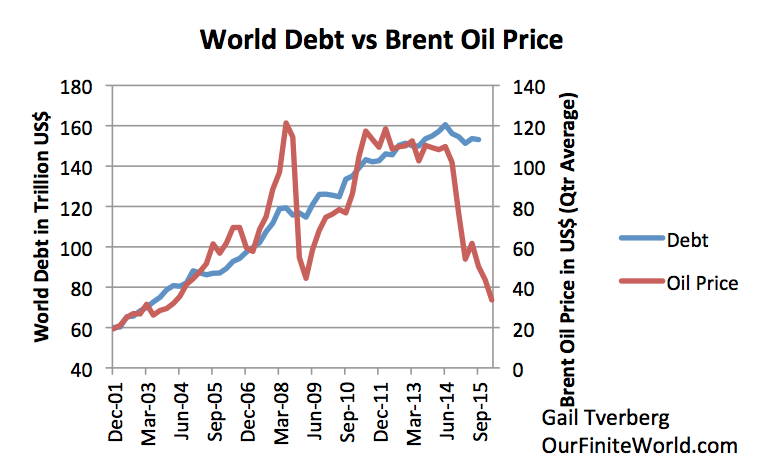
Figure 7 shows that world debt has been falling since June 30, 2014. This is precisely the time when world oil prices started falling.
Figure 6. Total non-financial world debt based on Bank for International Settlements data and average Brent oil price for the quarter, based on EIA data.
Figure 7. Total non-financial world debt based on Bank for International Settlements data and average Brent oil price for the quarter, based on EIA data.
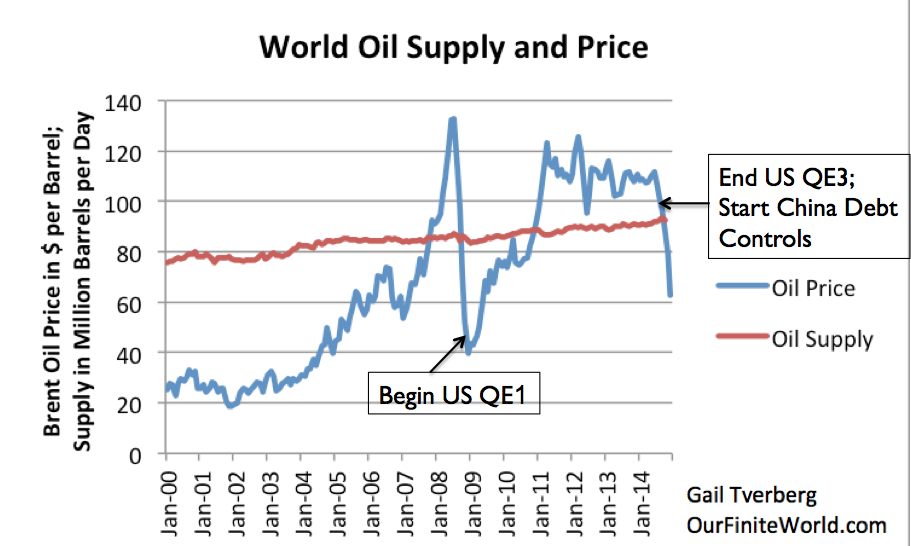
One reason for the fall in world debt, measured in US dollars, is the fact that the US dollar started rising relative to other currencies about this time. Oil is priced in dollars; if the US dollar rises relative to other currencies, it makes oil less affordable to those whose currencies have lower values. The big rise in the level of the dollar came when the US discontinued quantitative easing in 2014. World debt, as measured in US dollars, began to fall as the US dollar rose.
Figure 7. World Oil Supply (production including biofuels, natural gas liquids) and Brent monthly average spot prices, based on EIA data.
Figure 8. World Oil Supply (production including biofuels, natural gas liquids) and Brent monthly average spot prices, based on EIA data.
As long as the US dollar is high relative to other currencies, oil products remain less affordable, and demand tends to stay low.
Another issue that struck me in looking at world debt data is the way the growth in debt is distributed (Figure 9). Debt growth for households has been much lower than for businesses and governments.
Figure 8. World non-financial debt divided among debt of households, businesses, and governments, based on Bank for International Settlements data.
Figure 9. World non-financial debt divided among debt of households, businesses, and governments, based on Bank for International Settlements data.
Since March 31, 2008, non-financial debt of households has been close to flat. In fact, between June 30, 2014 and September 30, 2015,  it shrank by 6.3%. In contrast, non-financial debt of both businesses and governments has risen since March 31, 2008. Government debt has shrunk by 5.6% since June 30, 2014–almost as large a percentage drop as for household debt.
The issue that we need to be aware of is that consumers are the foundation of the economy. If their wages are not rising rapidly, and if their buying power (considering both debt and wages) is not rising by very much, they are not going to be buying very many new houses and cars–the big products that require oil consumption. Businesses may think that they can continue to grow without taking the consumer along, but very soon this growth proves to be a myth. Governments cannot grow without rising wages either, because the majority of their tax revenue comes from individuals, rather than corporations.
Today, there is a great deal of faith that oil prices will rise, if someone, somewhere, will reduce oil production. In fact, in order to bring oil demand back up to a level that commands a price over $100 per barrel, we need consumers who can afford to buy a growing quantity of goods made with oil products. To do this, we need to fix three related problems:
  • Low wages of many consumers
  • World debt that is no longer rising (especially for consumers)
  • A high dollar relative to other currencies
These problems are likely to be difficult to fix, so we should expect low oil prices, more or less indefinitely. Lack of oil supply may bring a temporary spike in oil prices, but it cannot fix a permanent problem with consumer spending around the world.

Tuesday, April 5, 2016

Triffin's Paradox Revisited: Crunch-Time For The U.S. Dollar & The Global Economy

Tyler Durden's picture

http://www.zerohedge.com/news/2016-04-05/triffins-paradox-revisited-crunch-time-us-dollar-global-economy
Submitted by Charles Hugh-Smith of OfTwoMinds blog,
The reality is that we're one panic away from foreign-exchange markets ripping free of central bank manipulation.
While all eyes on fixated on global stock markets as the measure of "prosperity" and "growth" (or is it hubris?), the larger force at work beneath the dovish cooing of central bankers is foreign exchange: the relative value of nations' currencies, which are influenced (like everything else) by supply and demand, which is in turn influenced by interest rates, perceived risk, asset purchases and sales by central banks and capital flows seeking the lowest possible risk and the highest possible return.
Which brings us to Triffin's Paradox, a topic I've covered for many years:
Understanding the "Exorbitant Privilege" of the U.S. Dollar (November 19, 2012)
The Federal Reserve, Interest Rates and Triffin's Paradox (November 19, 2015)
The core of Triffin's Paradox is that the issuer of a reserve currency must serve two entirely different sets of users: the domestic economy, and the international economy.
The U.S. dollar (USD) is the global economy's primary reserve currency. When the Federal Reserve lowered interest rates to zero (Zero Interest Rate Policy, ZIRP), it weakened the dollar relative to other currencies. In this ZIRP environment, it made sense to borrow dollars for next to nothing and use this free money to buy bonds and other assets in other currencies that paid higher yields. Many of these assets were in emerging market economies such as Brazil.
As a result of this enormous carry trade, an estimated $7 trillion was borrowed in USD and invested in other currencies/nations.
Once the Fed started making noises about "normalizing"/raising interest rates in the U.S. (i.e. signaling the markets that a trend change was at hand), the dollar strengthened and the carry trade started reversing: those who had bought assets in other currencies with borrowed USD started selling those assets, which pushed emerging market currencies and markets off a cliff.
Meanwhile, since China pegs its currency the yuan/RMB to the USD, the rising dollar dragged the yuan higher thanks to the peg. A strengthening yuan made China's exports more expensive and less competitive, the last thing China needed as its domestic credit bubble ran out of steam.
So while the Fed needed to "normalize" rates in the U.S. before the next recession required more Fed stimulus, it also needed to weaken the USD to protect China from a destabilizing currency devaluation.
Those holding millions of soon-to-be-devalued yuan in China were naturally anxious to convert their yuan into USD before the devaluation robbed them of 25% of the purchasing power of their money, and this has created an unprecedented capital flow of cash out of China and into USD and other Western assets, such as chateaux in France, homes in Vancouver B.C., etc.
This mad rush of capital out of China is adding another destabilizing factor to China's already wobbly debt bubble economy, and China's weakness has weakened an already wobbly global economy crippled by stagnation and the decline of emerging markets and commodities--two consequences of the rising USD.
This has created a no-win conundrum for the Fed: if it normalizes rates (as it should, after seven years of ZIRP and stimulus) in the domestic U.S. economy, that will strengthen the USD, further pressuring China's yuan and emerging markets, which in turn will further pressure an already-tottering global economy.
There are no winners, regardless of what policy the Fed chooses to pursue. This is why we see such absurd waffling in the Fed: one statement suggests interest rates hikes are on the way, and the next dovish cooing suggests rate hikes are so far away that global markets can safely ignore the possibility.
This push-pull is reflected in the chart of the USD:

As the Fed waffles in response to global markets, the USD has swung up and down in a trading range.
Sorry, Fed: you can't have it both ways. Eventually, the domestic economy will pay the price of essentially zero interest rates, or China and the global economy will pay the price of a strengthening USD.
No nation ever achieved global hegemony by devaluing its currency. Hegemony requires a strong currency, for the ultimate arbitrage is trading fiat currency that has been created out of thin air for real commodities and goods.
Generating currency out of thin air and trading it for tangible goods is the definition of hegemony. Is there is any greater magic power than that?
In essence, the Fed must raise rates to strengthen the U.S. dollar (USD) to keep commodities such as oil cheap for American consumers. The most direct way to keep commodities cheap is to strengthen one's currency, which makes commodities extracted in other nations cheaper by raising the purchasing power of the domestic economy on the global stage.
Another critical element of U.S. hegemony is to be the dumping ground for the exports of our trading partners. By strengthening the dollar, the Fed increases the purchasing power of everyone who holds USD. This lowers the cost of goods imported from nations with weakening currencies, who are more than willing to trade their commodities and goods for USD.
What better way to keep bond yields low and stock valuations high than insuring a flow of capital into U.S.-denominated assets?
There is one more destabilizing possibility: the markets may push the USD higher, regardless of what the Fed says or does. The currency markets trade $5 trillion a day--more than the Fed's entire $4 trillion balance sheet.
Once traders realize China will have to devalue the yuan by a lot more than a few baby-step devaluations, the stampede into USD could overwhelm even coordinated interventions by central bankers.
Of course no central banker will ever admit that markets could wrest free of central bank control, but the reality is that we're one panic away from foreign-exchange markets ripping free of central bank manipulation.

Tuesday, February 9, 2016

Iran No Longer Accepting Dollars For Oil; Demanding Euros Instead

death-of-the-petrodollar
Even with a number of U.S. sanctions against Iran coming to an end, the Iranian government has recently made a very important decision in regards to its oil payment system and it could spell bad news for the United States. This is because Iran has apparently decided to no longer accept U.S. dollars for payment on both its new and outstanding oil sales. Instead it will receive its payment in euros.
Reuters has cited an official from the National Iranian Oil Company (NIOC) as stating that the new plan will apply to “newly signed deals” with France’s Total, Russia’s Lukoil, and Spain’s Cepsa.
Reuters quotes the official as saying that “In our invoices we mention a clause that buyers of our oil will have to pay in euros, considering the exchange rate versus the dollar around the time of delivery.”
In addition, Iran is also informing its trading partners, including India, that owe billions of dollars that it now prefers to be paid in euros instead of dollars.
“Iran shifted to the euro and cancelled trade in dollars because of political reasons,” the official source said, pointing out that this policy was concocted during the time of the sanctions.
Hossein Yaqoubi-Miab, the director for international affairs department of the Central Bank of Iran (CBI), has stated that plans have already been made to receive the euro payments from India which total about $6.5 billion.
Reuters also mentioned that India is currently working on a system that would involve the United Commercial Bank (UCO) and the IDBI Bank handling the payments to Iran.
The new Iranian policy of receiving payments in euros as opposed to dollars is one that is likely to upset the United States who has maintained relative dominance as the world reserve currency for decades, a position that has gradually begun to erode as free trade and global empire have caught up with the dwindling superpower.
Thus, the Iranian currency policy will be yet one more blow to the dollar as the world reserve currency and might possibly be a catalyst for further antagonism toward Iran on the part of the United States.
Image Credit
Brandon Turbeville – article archive here – is the author of seven books, Codex Alimentarius — The End of Health Freedom, 7 Real Conspiracies, Five Sense Solutions and Dispatches From a Dissident, volume 1and volume 2, The Road to Damascus: The Anglo-American Assault on Syria, and The Difference it Makes: 36 Reasons Why Hillary Clinton Should Never Be President. Turbeville has published over 650 articles dealing on a wide variety of subjects including health, economics, government corruption, and civil liberties. Brandon Turbeville’s radio show Truth on The Tracks can be found every Monday night 9 pm EST at UCYTV. His website is BrandonTurbeville.com He is available for radio and TV interviews. Please contact activistpost (at) gmail.com.
Courtesy of Activist Post.

Friday, January 15, 2016

The 'Real' Price Of Oil Is Below $17

Tyler Durden's picture

http://www.zerohedge.com/news/2016-01-14/real-price-oil-below-17
"You see a big destruction in the income of the oil and commodity producers," exclaims on analyst but, as Bloomberg notes, while oil prices flashing across traders' terminals are at the lowest in a decade, in real terms the collapse is considerably deeper. Adjusted for inflation, WTI is its lowest since 2002 and worse still Saudi Light Crude is trading at below $17 (in 1998 dollar terms) - the lowest since the 1980s...
Slumping prices are a critical signal that the boom in lending in China is “unwinding,” according to Adair Turner, chairman of the Institute for New Economic Thinking.
In fact, while sub-$30 per barrel oil sounds very scary, Saudi prices would be less than $17 a barrel when converted into dollar levels for 1998, the year oil sank to its lowest since the 1980s.


Slowing investment and construction in China, the world’s biggest energy user, is “sending an enormous deflationary impetus through to the world, and that is a significant part of what’s happening in this oil-price collapse,” Turner, former chairman of the U.K. Financial Services Authority, said in an interview with Bloomberg Television.
*  *  *
So while prices are very low any description, never forget about inflation - The Fed won't!

Financial Collapse Leads To War

Tyler Durden's picture

http://www.zerohedge.com/news/2016-01-14/financial-collapse-leads-war
Submitted by Dmitry Orlov via Club Orlov blog,
[With the new year, a sea change seems to have occurred in the financial markets: instead of “melting up,” the way they used to, they have started “melting down.” My original prediction is that this will lead to more armed conflict. Let's see if I was right.]
Scanning the headlines in the western mainstream press, and then peering behind the one-way mirror to compare that to the actual goings-on, one can't but get the impression that America's propagandists, and all those who follow in their wake, are struggling with all their might to concoct rationales for military action of one sort or another, be it supplying weapons to the largely defunct Ukrainian military, or staging parades of US military hardware and troops in the almost completely Russian town of Narva, in Estonia, a few hundred meters away from the Russian border, or putting US “advisers” in harm's way in parts of Iraq mostly controlled by Islamic militants.
The strenuous efforts to whip up Cold War-like hysteria in the face of an otherwise preoccupied and essentially passive Russia seems out of all proportion to the actual military threat Russia poses. (Yes, volunteers and ammo do filter into Ukraine across the Russian border, but that's about it.) Further south, the efforts to topple the government of Syria by aiding and arming Islamist radicals seem to be backfiring nicely. But that's the pattern, isn't it? What US military involvement in recent memory hasn't resulted in a fiasco? Maybe failure is not just an option, but more of a requirement?
Let's review. Afghanistan, after the longest military campaign in US history, is being handed back to the Taliban. Iraq no longer exists as a sovereign nation, but has fractured into three pieces, one of them controlled by radical Islamists. Egypt has been democratically reformed into a military dictatorship. Libya is a defunct state in the middle of a civil war. The Ukraine will soon be in a similar state; it has been reduced to pauper status in record time—less than a year. A recent government overthrow has caused Yemen to stop being US-friendly. Closer to home, things are going so well in the US-dominated Central American countries of Guatemala, Honduras and El Salvador that they have produced a flood of refugees, all trying to get into the US in the hopes of finding any sort of sanctuary.
Looking at this broad landscape of failure, there are two ways to interpret it. One is that the US officialdom is the most incompetent one imaginable, and can't ever get anything right. But another is that they do not succeed for a distinctly different reason: they don't succeed because results don't matter. You see, if failure were a problem, then there would be some sort of pressure coming from somewhere or other within the establishment, and that pressure to succeed might sporadically give rise to improved performance, leading to at least a few instances of success. But if in fact failure is no problem at all, and if instead there was some sort of pressure to fail, then we would see exactly what we do see.
In fact, a point can be made that it is the limited scope of failure that is the problem. This would explain the recent saber-rattling in the direction of Russia, accusing it of imperial ambitions (Russia is not interested in territorial gains), demonizing Vladimir Putin (who is effective and popular) and behaving provocatively along Russia's various borders (leaving Russia vaguely insulted but generally unconcerned). It can be argued that all the previous victims of US foreign policy—Afghanistan, Iraq, Libya, Syria, even the Ukraine—are too small to produce failure writ large enough to satisfy America's appetite for failure. Russia, on the other hand, especially when incentivized by thinking that it is standing up to some sort of new, American-style fascism, has the ability to deliver to the US a foreign policy failure that will dwarf all the previous ones.
Analysts have proposed a variety of explanations for America's hyperactive, oversized militarism. Here are the top three:
1. The US government has been captured by the military-industrial complex, which demands to be financed lavishly. Rationales are created artificially to achieve that result. But there does seem to be some sort of pressure to actually make weapons and field armies, because wouldn't it be far more cost-effective to achieve full-spectrum failure simply by stealing all the money and skip building the weapons systems altogether? So something else must be going on.

2. The US military posture is designed to assure Americans of their imagined “full-spectrum dominance” over the entire planet. But “full-spectrum dominance” sounds a little bit like “success,” whereas what we see is full-spectrum failure. Again, this story doesn't fit the facts.

3. The US acts militarily to defend the status of the US dollar as the global reserve currency. But the US dollar is slowly but surely losing its attractiveness as a reserve currency, as witnessed by China and Russia acting as swiftly as they can to unload their US dollar reserves, and to stockpile gold instead. Numerous other nations have entered into arrangements with each other to stop using the US dollar in international trade. The fact of the matter is, it doesn't take a huge military to flush one's national currency down the toilet, so, once again, something else must be going on.
There are many other explanations on offer as well, but none of them explain the fact that the goal of all this militarism seems to be to achieve failure.
Perhaps a simpler explanation would suffice? How about this one:
The US has surrendered its sovereignty to a clique of financial oligarchs. Having nobody at all to answer to, this American (and to some extent international) oligarchy has been ruining the financial condition of the country, running up staggering levels of debt, destroying savings and retirements, debasing the currency and so on. The inevitable end-game is that the Federal Reserve (along with the central banks of other “developed economies”) will end up buying up all the sovereign debt issuance with money they print for that purpose, and in the end this inevitably leads to hyperinflation and national bankruptcy. A very special set of conditions has prevented these two events from taking place thus far, but that doesn't mean that they won't, because that's what always happens, sooner or later.

Now, let's suppose a financial oligarchy has seized control of the country, and, since it can't control its own appetites, is running it into the ground. Then it would make sense for it to have some sort of back-up plan for when the whole financial house of cards falls apart. Ideally, this plan would effectively put down any chance of revolt of the downtrodden masses, and allow the oligarchy to maintain security and hold onto its wealth. Peacetime is fine for as long as it can placate the populace with bread and circuses, but when a financial calamity causes the economy to crater and bread and circuses turn scarce, a handy fallback is war.

Any rationale for war will do, be it terrorists foreign and domestic, Big Bad Russia, or hallucinated space aliens. Military success is unimportant, because failure is even better than success for maintaining order because it makes it possible to force through various emergency security measures. Various training runs, such as the military occupation of Boston following the staged bombings at the Boston Marathon, have already taken place. The surveillance infrastructure and the partially privatized prison-industrial complex are already in place for locking up the undesirables. A really huge failure would provide the best rationale for putting the economy on a war footing, imposing martial law, suppressing dissent, outlawing “extremist” political activity and so on.
And so perhaps that is what we should expect. Financial collapse is already baked in, and it's only a matter of time before it happens, and precipitates commercial collapse when global supply chains stop functioning. Political collapse will be resisted, and the way it will be resisted is by starting as many wars as possible, to produce a vast backdrop of failure to serve as a rationale for all sorts of “emergency measures,” all of which will have just one aim: to suppress rebellion and to keep the oligarchy in power. Outside the US, it will look like Americans blowing things up: countries, things, innocent bystanders, even themselves (because, you know, apparently that works too). From the outside looking into America's hall of one-way mirrors, it will look like a country gone mad; but then it already looks that way. And inside the hall of one-way mirrors it will look like valiant defenders of liberty battling implacable foes around the world. Most people will remain docile and just wave their little flags.
But I would venture to guess that at some point failure will translate into meta-failure: America will fail even at failing. I hope that there is something we can do to help this meta-failure of failure happen sooner rather than later.

Ron Paul Warns: "Watch The Petrodollar"

Tyler Durden's picture

http://www.zerohedge.com/news/2016-01-13/ron-paul-warns-watch-petrodollar
Submitted by Nick Giambruno via InternationalMan.com,
The chaos that one day will ensue from our 35-year experiment with worldwide fiat money will require a return to money of real value. We will know that day is approaching when oil-producing countries demand gold, or its equivalent, for their oil rather than dollars or euros. The sooner the better. - Ron Paul
Ron Paul is calling for the end of the petrodollar system. This system is one of the main reasons the U.S. dollar is the world’s premier reserve currency.
Essentially, Paul is saying that understanding the petrodollar system and the forces affecting it is the best way to predict when the U.S. dollar will collapse.
Paul and I discussed this extensively at one of the Casey Research Summits. He told me he stands by his assessment.

Nick Giambruno and Ron Paul
This is critically important. When the dollar loses its coveted status as the world’s reserve currency, the window of opportunity for Americans to protect their wealth from the U.S. government will definitively shut.
At that point, the U.S. government will implement the same destructive measures other desperate governments have used throughout history: overt capital controls, wealth confiscation, people controls, price and wage controls, pension nationalizations, etc.
The dollar’s demise will wipe out the wealth of a lot of people. But it will also trigger political and social consequences likely to be far more damaging than the financial fallout.
The two key takeaways are:
  1. The U.S. dollar’s status as the premier reserve currency is tied to the petrodollar system.
  1. The sustainability of the petrodollar system relies on volatile geopolitics in the Middle East (where I lived and worked for several years).

From Bretton Woods to the Petrodollar

The Bretton Woods international monetary system, which the Allied powers created in 1944, turned the dollar into the world’s premier reserve currency.
After WWII, the U.S. had by far the largest gold reserves in the world (around 706 million ounces). These large reserves - in addition to winning the war - allowed the U.S. to reconstruct the global monetary system around the dollar.
The Bretton Woods system tied virtually every country’s currency to the U.S. dollar through a fixed exchange rate. It also tied the U.S. dollar to gold at a fixed exchange rate.
Countries around the world stored dollars for international trade or to exchange with the U.S. government at the official rate for gold ($35 an ounce at the time).
By the late 1960s, excessive spending on welfare and warfare, combined with the Federal Reserve monetizing the deficits, drastically increased the number of dollars in circulation relative to the gold backing them.
Naturally, this made other countries exchange more dollars for gold at an increasing rate. This drained the U.S. gold supply. It dropped from 706 million ounces at the end of WWII to around 286 million ounces in 1971 (a figure supposedly held constant to this day).
To stop the drain, President Nixon ended the dollar’s convertibility for gold in 1971. This ended the Bretton Woods system.
In other words, the U.S. government defaulted on its promise to back the dollar with gold. This eliminated the main motivation for other countries to hold large U.S. dollar reserves and use the U.S. dollar for international trade.
With the dollar no longer convertible into gold, demand for dollars by foreign nations was sure to fall, and with it, the dollar’s purchasing power.
OPEC, a group of oil-producing countries, passed numerous resolutions after the end of Bretton Woods, stating its need to maintain the real value of its earnings. It even discussed accepting gold for oil. Ultimately, OPEC significantly increased the nominal dollar price of oil.
For the dollar to maintain its status as the world’s reserve currency, the U.S. would have to concoct a new arrangement that gave foreign countries a compelling reason to hold and use dollars.

The Petrodollar System

From 1972 to 1974, the U.S. government made a series of agreements with Saudi Arabia. These agreements created the petrodollar system.
The U.S. government chose Saudi Arabia because of its vast petroleum reserves, its dominant position in OPEC, and the (correct) perception that the Saudi royal family was corruptible.
In essence, the petrodollar system was an agreement that the U.S. would guarantee the survival of the House of Saud. In exchange, Saudi Arabia would:
  1. Use its dominant position in OPEC to ensure that all oil transactions would happen in U.S. dollars.
  1. Invest a large amount of its dollars from oil revenue in U.S. Treasury securities and use the interest payments from those securities to pay U.S. companies to modernize the infrastructure of Saudi Arabia.
  1. Guarantee the price of oil within limits acceptable to the U.S. and prevent another oil embargo by other OPEC members.
Oil is the world’s most traded and most strategic commodity. Needing to use dollars for oil transactions is a very compelling reason for foreign countries to keep large U.S. dollar reserves.
For example, if Italy wants to buy oil from Kuwait, it has to purchase U.S. dollars on the foreign exchange market to pay for the oil first. This creates an artificial market for U.S. dollars that would not otherwise exist.
The demand is artificial because the U.S. dollar is just a middleman in a transaction that has nothing to do with a U.S. product or service. Ultimately, it translates into increased purchasing power and a deeper, more liquid market for the U.S. dollar and U.S. Treasuries.
Additionally, the U.S. has the unique privilege of not having to use foreign currency to buy imports, including oil. Instead, it gets to use its own currency, which it can print.
It’s hard to overstate how much the petrodollar system benefits the U.S. dollar. It’s allowed the U.S. government and many Americans to live beyond their means for decades.

What to Watch For

The geopolitical sands of the Middle East are rapidly shifting.
Saudi Arabia’s strategic regional position is weakening. Iran, which is notably not part of the petrodollar system, is on the rise. U.S. military interventions are failing. And the emerging BRICS countries are creating potential alternatives to U.S.-dominated economic/security arrangements. This all affects the sustainability of the petrodollar system.
I’m watching the deteriorating relationship between the U.S. and Saudi Arabia with a particularly close eye.
The Saudis are furious because they don’t think the U.S. is holding up its end of the petrodollar deal by more aggressively attacking their regional rivals.
This suggests that they might not uphold their part of the deal much longer, namely selling their oil exclusively in U.S. dollars.
The Saudis have even suggested a “major shift” is under way in their relationship with the U.S. To date, though, they haven’t matched their words with action, so it may just be a temper tantrum or a bluff.
The Saudis need an outside protector. So far, they haven’t found any suitable replacements for the U.S. In any case, they’re using truly unprecedented language.
This situation may reach a turning point when U.S. officials start expounding on the need to transform the monarchy in Saudi Arabia into a “democracy.” But don’t count on that happening as long as Saudi oil sells exclusively for U.S. dollars.
Regardless, the chances that the Kingdom might implode on its own are growing.
For the first time in decades, observers are calling into question the viability of the Saudi currency, the riyal. The Saudi central bank currently pegs the riyal at a rate of 3.75 riyals per U.S. dollar.
The Saudi government spends a ton of money on welfare to keep its citizens sedated. Lower oil prices plus the cost of their mischief in the region are cutting deep into government revenue. So there’s less money to spend on welfare.
There’s a serious crunch in the Saudi budget. They’ve only been able to stay afloat by draining their foreign exchange reserves. That threatens their currency peg.
Recently, Saudi officials have begun telling the media that the currency peg is fine and there’s nothing to worry about. That’s another clue that there’s trouble. Official government denial is almost always a sign of the opposite. It’s like the old saying: “Believe nothing until it has been officially denied.”
If there were a convenient way to short the Saudi riyal, I would do it in a heartbeat.

Timing the Collapse

Long before Nixon ended the Bretton Woods system in 1971, it was clear that a paradigm shift in the global monetary system was inevitable.
Today, another paradigm shift seems inevitable. As Ron Paul explained, there’s one sure way to know when that shift is imminent:
We will know that day is approaching when oil-producing countries demand gold, or its equivalent, for their oil rather than dollars or euros.
It’s very possible that, one day soon, Americans will wake up to a new reality, just as they did in 1971 when Nixon severed the dollar’s final link to gold.
The petrodollar system has allowed the U.S. government and many U.S. citizens to live way beyond their means for decades. It also gives the U.S. unchecked geopolitical leverage. The U.S. can exclude virtually any country from the U.S. dollar-based financial system…and, by extension, from the vast majority of international trade.
The U.S. takes this unique position for granted. But it will disappear once the dollar loses its premier status.
This will likely be the tipping point…
Afterward, the U.S. government will be desperate enough to implement capital controls, people controls, nationalization of retirement savings, and other forms of wealth confiscation.
I urge you to prepare for the economic and sociopolitical fallout while you still can. Expect bigger government, less freedom, shrinking prosperity…and possibly worse.
It’s probably not going to happen tomorrow. But it’s clear where the trend is headed.
Once the petrodollar system kicks the bucket and the dollar loses its status as the world’s premier reserve currency, you will have few, if any, options to protect yourself.
This is why it’s essential to act before that happens.
The sad truth is, most people have no idea how bad things could get, let alone how to prepare…
Yet there are straightforward steps you can start taking today to protect your savings and yourself from the financial and sociopolitical effects of the collapse of the petrodollar.
This recently released video will show you where to begin. Click here to watch it now.